Udeesha Tomar
AVP - Strategy and Solutions
Leading procurement research solutions across chemicals, materials, and food & beverages, with expertise in price forecasting and market analytics.

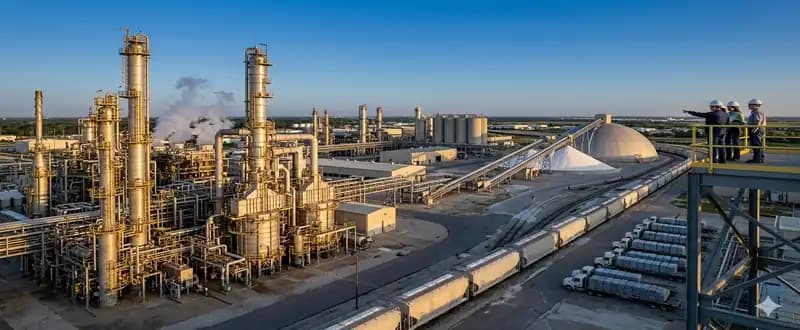
Ethylene prices moved higher in both Asia and Europe through late May 2026 as costlier naphtha feedstock and reduced cracker operating rates tightened the supply side. Northeast Asian ethylene was assessed near $0.94 per kilogram, up about 3.3%, while European material reached roughly $1.50 per kilogram, up 5.6%. The gains carried through despite an underlying European market that has been weighed down by structural oversupply and soft downstream demand for much of the past year.
Feedstock economics did most of the work. Higher naphtha costs, driven in part by crude oil strength after disruption to roughly 20% of global oil and LNG flows through the Strait of Hormuz, raised the cost of cracking and separation. Energy-intensive production amplified the effect for steam cracker operators, who already faced thin margins. Reduced run rates and ongoing capacity rationalization across Japan and South Korea, targeting cuts of about 20-28%, limited spot availability and supported firmer pricing even where demand was unremarkable.
The regional split remains wide. European cracker utilization sat near 75% through 2025, reflecting weak demand and persistent oversupply, which kept the market subdued before feedstock costs pushed prices up. Asian fundamentals tightened faster as operators pared output and feedstock flows became less certain. The result is an ethylene market where cost-push rather than demand-pull is setting the direction, a pattern that tends to compress margins for downstream converters who cannot pass through higher input costs immediately.
Request the Latest Ethylene Prices Data - Access Price Insights Now
Ethylene sits at the base of a wide product tree, feeding polyethylene, ethylene glycol, ethylene oxide, styrene and PVC chains. Higher ethylene therefore flows quickly into packaging films, bottles, antifreeze, textiles and construction materials. For buyers in these segments, the late-May move signals rising raw material costs that will work through contract formulas over the coming weeks, especially where pricing is indexed to monomer benchmarks.
Procurement teams should review how their supply contracts handle feedstock-driven increases and whether force majeure exposure exists in their supplier base, given the disruption to Middle East flows. Buyers able to source from regions with surplus capacity, such as parts of Europe where oversupply persists, may find better terms than those tied to tightening Asian markets. Tracking naphtha prices, crude movements and cracker operating rates offers the most direct early warning of where ethylene heads next. With capacity cuts in northeast Asia set to continue, the supply cushion that once absorbed feedstock shocks is thinner than in past cycles, which raises the risk of sharper moves if crude stays elevated.
AVP - Strategy and Solutions
Leading procurement research solutions across chemicals, materials, and food & beverages, with expertise in price forecasting and market analytics.

We are Just a Text away