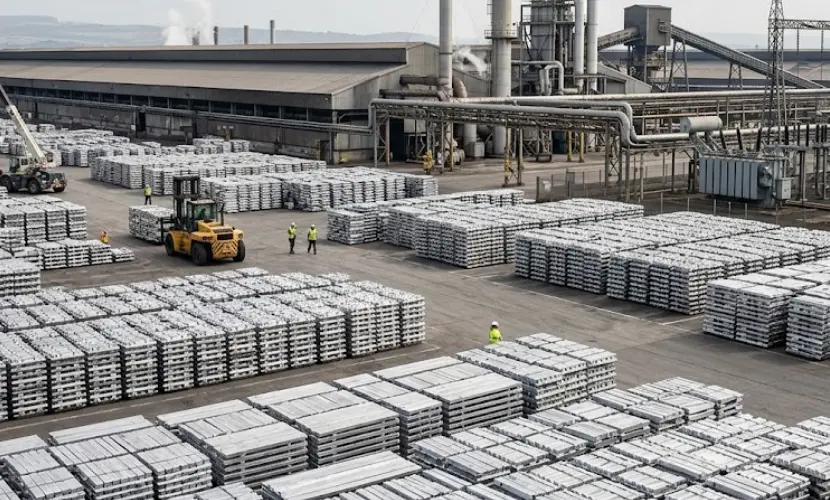
- Global aluminium cash markets stayed firm through much of Q2’26 as tight inventories and disrupted primary supply supported values before conditions eased in June.
- Feedstock and production costs remained elevated as energy-intensive smelting and recycling faced higher operating costs, while improving supply expectations reduced late-quarter pressure.
- Downstream demand remained supported by automotive, packaging, and pharmaceutical foil applications, although expanding primary output in key producing markets capped stronger gains.
In China, Aluminium (Cash) prices remained almost stable, moving from ~USD 1,336.79/MT in May to ~USD 1,337.00/MT in June. China avoided the sharper international rise because primary aluminium production expanded, improving domestic availability even as global supply tightened. India showed a mild upward shift, with prices increasing from ~USD 1,404.13/MT to ~USD 1,424.30/MT, reflecting a ~1.4% gain in the last two months from the quarter. Higher global replacement and logistics costs supported the increase, while steady demand from automotive and pharmaceutical packaging provided additional support. In Germany, Aluminium (Cash) prices moved higher during the period, rising from ~USD 1,430.24/MT in May to ~USD 1,458.30/MT in June. European availability tightened as disruption to Gulf production reduced imported primary metal, while elevated energy and recycling costs strengthened replacement values. However, expectations of improving Gulf shipments eased some supply concerns during June, preventing a stronger quarter-end rise.