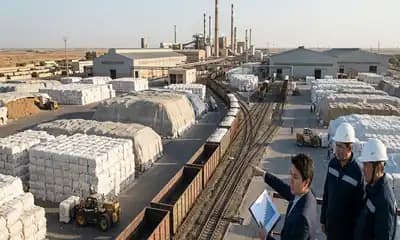
- Cotton lint markets remained broadly stable during Q2 2026, with cautious textile buying limiting gains despite tighter crop expectations and reduced global availability.
- Crop availability and harvesting expectations influenced raw cotton supply, while improved import access in some markets helped reduce procurement pressure for spinning mills.
- Textile, apparel and home-furnishing demand remained uneven, with mills largely maintaining need-based purchases instead of rebuilding inventories aggressively.
In the Chinese markets, Cotton Lint prices reduced slightly to about USD 2,595/MT in June from around USD 2,611/MT in the previous month. Chinese cotton lint conditions remained soft as textile mills maintained cautious procurement during the seasonal slowdown in apparel and home-textile orders. Expectations of lower domestic crop availability provided some support, but adequate inventories and subdued downstream orders prevented sellers from achieving stronger increases. Spinners focused on immediate production requirements rather than inventory accumulation, keeping market movement limited. Indian Cotton Lint monthly average prices were around USD 2,678/MT in May and approx. USD 2,683/MT during the second quarter of 2026. Cotton prices in the region were sustained at slightly higher level due to relatively good consumption of the commodity by spinning mills and higher export demand. However, greater availability of imported cotton prevented any further rise in prices in the quarter. Mills were conscious of margins on yarn and export orders, thus absorbing only as much as needed.