- Norske Skog will convert PM 6 at Saugbrugs mill to kraftliner and SC paper by first half 2028
- PM 4 and PM 5 at Saugbrugs will shut down once converted PM 6 starts production
- Gulf testliner index fell 0.70 percent to about 495.85 dollars per tonne in September
- Gulf fluting index slipped 0.37 percent to about 470.08 dollars per tonne for September
- UAE diesel climbed 26 percent from August to October, lifting regional freight costs
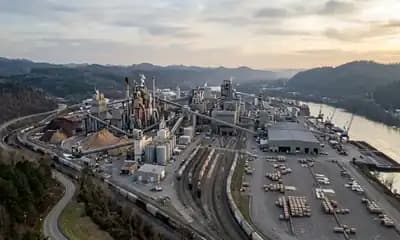
Global kraft linerboard markets moved through early October 2026 with regional divergence sharpening across North America, Europe, and the Gulf Cooperation Council, as capacity decisions, logistics costs, and softer physical demand each pulled prices in different directions. On October 8, Norske Skog confirmed that it will convert the decommissioned PM 6 machine at its Saugbrugs mill in Norway to produce thermomechanical pulp based kraftliner and supercalendered paper. The project aims to bring PM 6 online in the first half of 2028, with the Saugbrugs site set to make its first entry into the kraftliner market from that date. Once PM 6 ramps up, Norske Skog will close PM 4 and PM 5, which currently produce supercalendered paper, redirecting the overall mill output toward corrugated packaging grades.
The Saugbrugs decision marks the latest in a wave of capacity shifts in Europe, where producers continue to retool graphic paper machines for packaging grades in response to declining publication demand and firm structural growth in corrugated case material. Combined with earlier closures at Folbb's Baiersbronn site and ongoing uncertainty at Folding Boxboard Eerbeek, the European containerboard supply map is set to look materially different by late 2027.
Request the Latest Kraft Linerboard Prices Data - Access Price Insights Now
Across the Gulf Cooperation Council, kraft linerboard proxy indices moved lower through September. The Gulf testliner index fell 0.70 percent to about 495.85 United States dollars per tonne by the end of the month, down from 499.37 dollars at the start of September. The Gulf fluting index slipped 0.37 percent to 470.08 dollars per tonne. Demand across the region was broadly stable to higher, with back to school converter orders providing a floor, though Saudi Arabian consumption stayed below historical norms and the United Arab Emirates saw stable but subdued volumes.
Logistics continued to shape the Gulf picture more than fundamentals. Strait of Hormuz disruptions kept trade flows unsettled, Jeddah port congestion raised freight costs, and a regional truck shortage lifted road transport rates. United Arab Emirates diesel climbed 26 percent from August to October, pushing retail prices from 3.80 to 4.80 dirhams per litre. Recycled paper feedstock prices stayed flat in Saudi Arabia, while UAE recycled paper eased by about 5 to 10 dollars per tonne on continued export friction. One major regional producer delayed trial production at a new recycled corrugated case material line to the first quarter of 2028 citing supply chain and cost pressure.
For procurement teams in packaging, e commerce, and consumer goods supply chains, the near term action is to confirm fourth quarter 2026 and first quarter 2027 kraft linerboard coverage before European capacity shifts and Gulf logistics costs push landed prices higher. North American converters should prepare for continued firm pricing after the earlier 140 dollar per tonne producer increases, while importers in India and Southeast Asia should test European recycled grades at current softer levels. Automotive, food, and electronics brand owners should stress test their fourth quarter cost models against a scenario where Gulf and European kraft liner values converge back toward 510 dollars per tonne through December.