Prakhar Panchbhaiya
Assistant Manager: Business Insights and Content
Supporting procurement teams with category intelligence, market research, price trends, supply-demand analysis, and strategic sourcing insights across key industries.


The natural rubber market entered the second half of October 2026 at a multi-year high before a sharp pullback trimmed the gains in Qingdao spot through the middle of the window. Qingdao spot offers for mixed and compound rubber were cut by CNY 450 to 600 per tonne on October 15, with cumulative losses of more than CNY 1,000 per tonne over three trading sessions. By October 16, 2024-grade material in Qingdao was quoted at CNY 19,000 to 19,300 per tonne, 2025-grade at CNY 19,150 to 19,400 per tonne, and Vietnamese 3L at CNY 20,250 to 20,400 per tonne. Thai smoked sheet reference stood at THB 90.50 per kilogram on October 14, broadly steady on the day. The move came off a strong run earlier in October, when SMR 20 in Malaysia had reached 1,074.5 sen per kilogram on October 12, its highest level since May 2012, and bulk latex had firmed to 777 sen per kilogram.
Request the Latest Natural Rubber Prices Data - Access Price Insights Now
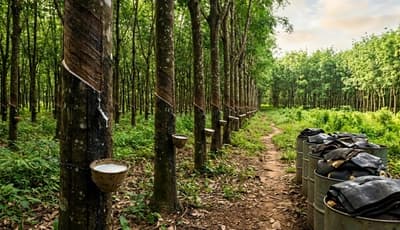
Supply-side support remained in place but weakened as the fortnight progressed. Thai rain and flood warnings into mid-October constrained tapping in southern producing provinces, and about 23,000 hectares of plantation area had been affected by weather disruption in late September. The Rubber Trade Association had flagged tree aging and low replanting rates as structural supports into early 2027, and projections of a stronger El Nino also added to the longer-term bullish narrative. Working against those supports, downstream tyre demand failed to validate the price level. China's September rubber imports came in at 588,000 tonnes, down 20.8 percent year on year, and projected September Chinese passenger car retail sales at 1.618 million units were down 28 percent year on year. US tyre imports for January to August 2026 were 186.22 million units, down 4 percent year on year, confirming softer demand pull.
For procurement teams, the setup argues for staggered buying rather than full cover at the top. Tyre makers and industrial rubber goods converters in India, Southeast Asia, and Europe should split fourth-quarter requirements between Thai smoked sheet, Malaysian SMR 20, and Vietnamese block, taking advantage of the Qingdao spot pullback to secure cargoes ex-store without chasing Malaysian port offers. Buyers with longer-dated 2027 contracts should press for formula-linked pricing rather than fixed premiums to capture both the weather-driven supply swing and the softer Chinese and US tyre demand signals, and should retain backup allocation across origins to protect against El Nino shocks in the first quarter.
Assistant Manager: Business Insights and Content
Supporting procurement teams with category intelligence, market research, price trends, supply-demand analysis, and strategic sourcing insights across key industries.


We are Just a Text away