- Western Australian barley at Albany moved from 325 to 329 Australian dollars per tonne through October 6
- Eastern Australian barley track Geelong held near 290 Australian dollars per tonne
- Rain across South Australia and Victoria gave timely relief to southern drought stressed crops
- Spot delivered homes stayed hard to find with many bids skewed to deferred positions
- Chinese interest in Australian wheat was preliminary but visible across the first week of October
Australian barley markets moved into the first week of October 2026 with firmer wholesale values in the west and a mix of early harvest pressure and tight spot availability in the east. On October 1, Western Australian barley at Albany was quoted close to 325 Australian dollars per tonne, with the price edging higher to around 329 Australian dollars per tonne by October 6. Eastern Australian barley track Geelong held near 290 Australian dollars per tonne through the opening of the month, with the softer eastern print reflecting both longer carry and continued pressure from new crop expectations in the southern growing belt.
Wider grain complex activity set the direction. Wheat moved higher through the first days of October as Black Sea conflict risk returned to the headlines and buyers rechecked origin diversification. Australian canola also stayed firm, with Western Australian new crop quotes near 865 to 882 Australian dollars per tonne and Eastern Australian conventional canola trading closer to 817 Australian dollars per tonne. Lentils and other pulse markets held constructive bias, with old crop bids around 610 Australian dollars per tonne delivered port and new crop near 600 Australian dollars.
Request the Latest Barley Prices Data - Access Price Insights Now
Weather and sowing stayed supportive. Rain started falling across South Australia overnight on October 1 and spread into Victoria during the day, giving a timely lift to drought stressed crops in the southern Mallee and Wimmera. Over the following week, additional rainfall of 10 to 35 millimetres was expected across eastern Australia, helping grain fill in the northern belt. Northern Queensland harvest activity had already begun despite a 10 to 20 millimetre event the week before. Traders reported that spot delivered homes were difficult to find in parts of the country, with many bids skewed to deferred rather than prompt positions.
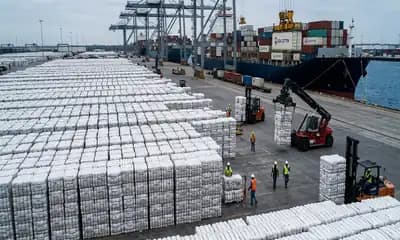
The export story stayed firm. Chinese interest in Australian wheat was preliminary but visible, with buyers testing offers after a long period of lighter engagement. Barley export flows to China, Southeast Asia, and the Middle East held steady, with Saudi Arabian coarse grain tender expectations keeping sentiment supportive. European and Russian competition continued to cap upside at the top of the Australian offer range.
For procurement teams in feed, malt, and brewing supply chains, the message is to lock in October and November Australian barley cover before harvest logistics tighten further. Feedlot and dairy buyers should confirm forward volumes while basis is still workable, as spot delivered availability is already thin in parts of the country. Malt barley buyers should stress test fourth quarter cost models against a scenario where east coast rainfall deepens or weather disrupts the northern Queensland harvest, which could lift Albany quotes toward 340 to 350 Australian dollars per tonne by late October.