Prakhar Panchbhaiya
Assistant Manager: Business Insights and Content
Supporting procurement teams with category intelligence, market research, price trends, supply-demand analysis, and strategic sourcing insights across key industries.

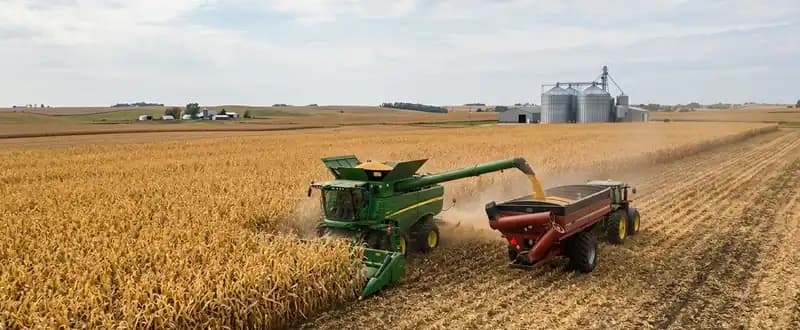
Chicago corn futures moved through a choppy start to October 2026, with the December contract firming on October 1 before pulling back sharply through the first week of the month. The December contract settled at about 5.02 cents per bushel on October 1, up 1.5 cents on the day, then eased to about 4.97 cents by October 2 and continued the slide into the following week on heavy quarterly stocks data and advancing harvest pressure. By the start of trading on October 5, support in the December contract was mapped close to 4.92 cents per bushel.
The main driver was the quarterly stocks report, which placed United States corn inventories at about 2.095 billion bushels. The reading came in above trade expectations and triggered a wide sell off through the row crop complex. Soybean oil, soybean meal, and wheat all gave background over the same window, with the Chicago wheat December contract pulling back to the 6.83 cent per bushel area even as a modest Saudi Arabian wheat tender provided some demand side cushion. Harvest progress for United States corn reached about 18 percent complete by the beginning of October, running close to the five-year average.
Request the Latest Corn Prices Data - Access Price Insights Now
Export activity provided a mixed picture. Private exporters announced sales of about 129,540 tonnes of United States corn to Mexico during the first week of October, confirming the steady underlying pull from the primary southern buyer. Chinese appetite stayed cautious, with new crop corn commitments slower to appear than for soybeans. Weekly export inspections tracked above year ago levels, with elevators at the Gulf and Pacific Northwest reporting a healthy loading cadence through the holiday weekend.
Weather patterns favored harvest. Dry conditions throughout the Midwest kept combining progress on track, with Iowa, Illinois, and Nebraska running at or ahead of the five-year pace. Northern areas were set to receive cooler and drier weather, while southern zones stayed broadly dry, both of which support quick harvest even if yields come in near trend. The next official supply and demand estimate was expected within the week, with traders split on whether yields would be trimmed further.
For procurement teams in ethanol, feed, starch, and sweetener supply chains, the near-term action is to lock in October and November corn coverage while futures sit close to multi-week lows. Ethanol plants should watch grind margins carefully as corn eases, since any renewed run rate increase would tighten the local basis. Feed millers in the eastern United States and in Mexico should test forward basis offers before harvest truck movement peaks. Starch and sweetener buyers should stress test fourth quarter cost models against a scenario where December Chicago corn consolidates between 4.90 and 5.10 cents per bushel through late October.
Assistant Manager: Business Insights and Content
Supporting procurement teams with category intelligence, market research, price trends, supply-demand analysis, and strategic sourcing insights across key industries.
We are Just a Text away