Prakhar Panchbhaiya
Assistant Manager: Business Insights and Content
Supporting procurement teams with category intelligence, market research, price trends, supply-demand analysis, and strategic sourcing insights across key industries.

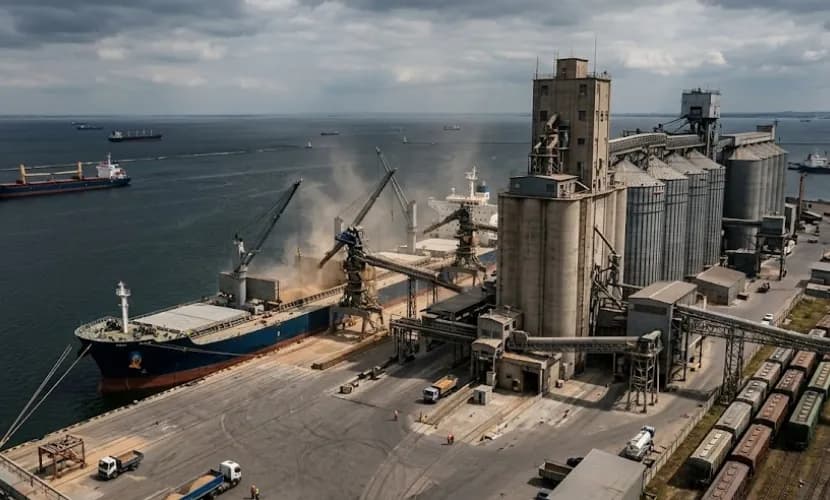
Global wheat markets moved higher during the first week of October 2026 as Black Sea shipping disruptions pulled buyers back toward United States, Australian, and Argentine origins. Chicago Board of Trade December wheat traded close to 6.89 cents per bushel on October 5, recovering from a multi week low set the week before, before easing again on long liquidation ahead of the fresh United States supply and demand round. By October 8, support in the Chicago December contract was mapped near 671 cents and resistance near 711 cents, with Kansas City hard red winter wheat finding support near 729 cents and resistance near 780 cents.
The Black Sea story remained at the center of the price action. Russian ports on the Azov and Black Sea were expected to stay closed into 2027, and Moscow rejected proposals for a truce in Black Sea attacks earlier in the week. A private Russian forecast cut 2026 to 2027 grain export expectations to about 44.7 million tonnes, down from a prior 49.4 million tonne call. Asian and North African buyers continued to look at Australian Premium White wheat and Argentine origin for coverage, while cargo flows out of Ukraine remained patchy.
Request the Latest Wheat Prices Data - Access Price Insights Now
United States supply fundamentals offered a mixed backdrop. Quarterly stocks for all wheat were reported at about 1.845 billion bushels, in line with trade estimates and signaling steady utilization. Winter wheat planting was running close to the historical pace, with growers in the southern Great Plains testing conditions after a wetter than usual summer. Export inspection data stayed close to the five year average, with Egyptian, Nigerian, and Southeast Asian buyers active in the Gulf and Pacific Northwest loading program.
Cross grain complex pressure capped the upside. Weekly corn stocks of about 2.095 billion bushels came in above expectations, forcing a wave of long liquidation that pulled wheat lower on October 2 and again on October 3. A stronger United States dollar also raised the landed cost of wheat for international buyers through the first week of October, keeping competing Russian and European offers more attractive on paper despite the shipping risk.
For procurement teams in milling, feed, and food ingredient supply chains, the near term action is to secure October and November wheat coverage while futures still sit close to the lower half of the recent range. Flour millers in India, Southeast Asia, and the Middle East should confirm bilateral tenders for November and December shipment. Feed buyers should stress test fourth quarter cost models against a scenario where Chicago December wheat firms back toward 730 cents per bushel if Black Sea shipping risk escalates further or if the next official supply and demand estimate trims global stocks.
Assistant Manager: Business Insights and Content
Supporting procurement teams with category intelligence, market research, price trends, supply-demand analysis, and strategic sourcing insights across key industries.
We are Just a Text away